Get the most current Credit Dispute Letter form now and subscribe to download
A credit dispute letter is an important legal tool for protecting your credit score. It’s used to claim a credit report error and encourage a credit reporting agency to delete or correct inaccurate or fraudulent entries.
If you notice incorrect entries on your own report, writing a dispute letter from scratch can feel overwhelming, especially if you’ve never filed one before. To help you create a letter that works, our platform offers a comprehensive credit dispute letter form that you can fill out and sign right in your browser.
What Is a Credit Dispute Letter?
A credit dispute letter is a formal request used to initiate a credit dispute.
Credit dispute meaning: The process of contesting the information on a credit report that appears inaccurate, fraudulent, or incomplete. A dispute request is forwarded either to a credit reporting agency, such as Equifax, Experian, or TransUnion, or straight to a data furnisher or creditor with the goal of protecting the consumer’s finances and credit score.
Types of information that you can dispute include:
Incorrect names
Outdated mailing addresses
Old or false employer details
Wrong account ownership details
Incorrect current balances
False credit limits
Accounts marked in collections or late by mistake
Outdated negative financial data (e.g., old bankruptcies)
Wrong payment histories
Duplicate entries
Accounts and/or credit lines opened through identity theft
Fraudulent charges
The right to initiate a credit dispute is granted through the Fair Credit Reporting Act (FCRA). Under this federal law, reporting agencies and data providers are required to investigate and, if the information is found to be inaccurate or cannot be verified, correct or remove it.
Importantly, a credit dispute is not the same as a chargeback. A dispute aims to protect your financial profile by removing inaccurate, fraudulent, or incomplete information from it. A chargeback is a request to refund a specific transaction sent to merchants or banks.
What a Credit Dispute Letter Should Include
Although the Fair Credit Reporting Act generally requires the credit reporting agency to initiate a free investigation of incomplete or inaccurate information in the event of receiving a consumer's notice, the FCRA §611 details that the agency may consider a dispute frivolous or irrelevant under certain conditions, including when a consumer fails to provide sufficient information for investigation. In this case, a consumer will receive a notice of determination that clarifies the reasons for the determination and identification of any additional information required to investigate the dispute.
In order to create credit dispute letters that work and prevent your request from being considered frivolous or irrelevant, it’s important to provide complete and specific details about the disputed information.
Required Information in a Dispute Letter
A standard letter written to dispute a credit report consists of 3 main sections:
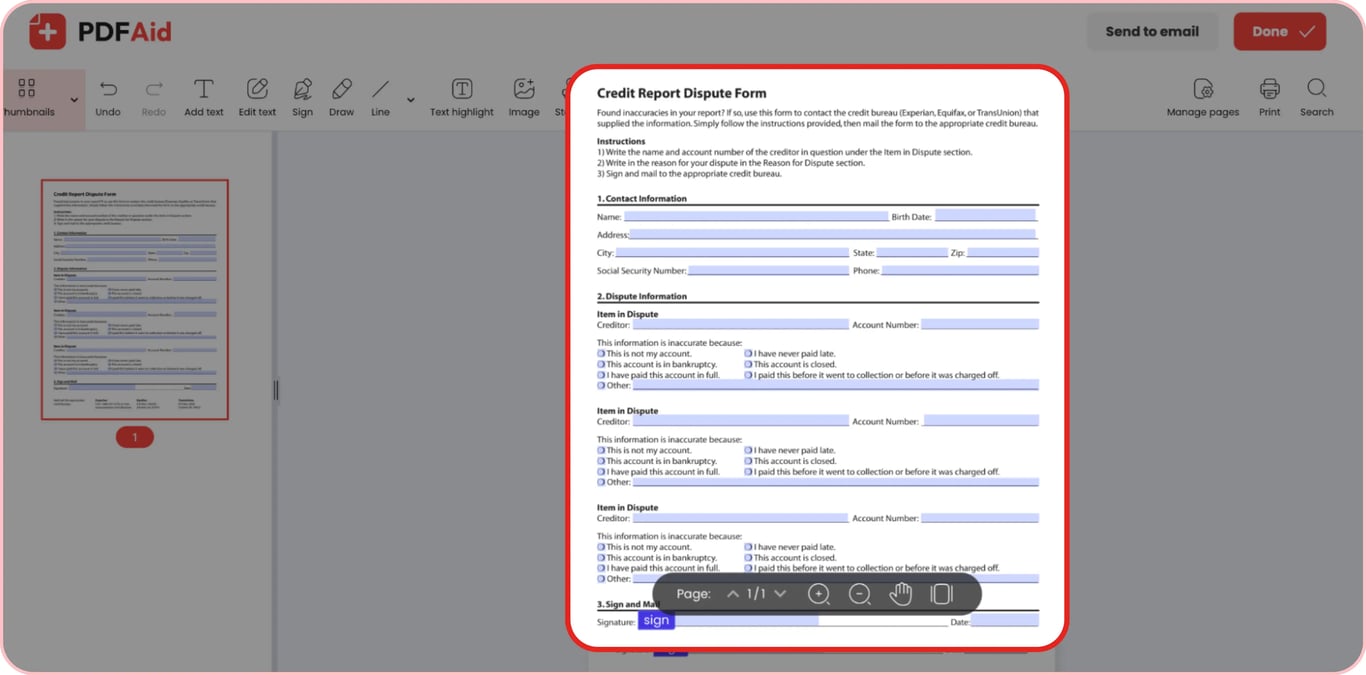
The Contact Information block provides the basic information needed to identify the consumer, such as:
Full legal name
Birth date
Mailing address
Social security number
Phone number
The Dispute Information section clarifies the specific items the consumer wants to dispute. Our PDF form includes three dispute item blocks, each including the following data:
Creditor (full name of the institution/company that is reporting the disputed item)
Account number
A list of reasons why the information in dispute is inaccurate (e.g., this is not your account, the account is in bankruptcy, the account is closed, etc.)
If you want to dispute inaccurate information for a reason that’s not listed, there is an additional blank field next to the option called “Other.” If you check it, you must provide a clear wording of what is inaccurate and a request to delete or correct this piece of data in your report.
The Sign and Mail is the last section of the letter where a consumer must place their signature and the date of signing. Additionally, this section provides the contact details of the three major agencies that you can file your letter with.
How to Dispute Errors on Your Credit Report
In general, it takes 6 steps to file a credit dispute, regardless of the type of error:
Step 1. Get your personal credit report from an agency and find an incorrect entry.
Step 2. Collect supporting documents and evidence that confirm that a particular entry is invalid.
Step 3. Build a dispute letter that contains all essential data as described above.
Step 4. Submit your letter and supporting documents to a credit reporting agency.
Step 5. Wait for the agency to receive your request and run an investigation.
Step 6. Get an investigation decision and request a method of verification, or file a complaint with the CFPB if you believe that the issue persists.
How to Dispute Collections and Charge-Offs
If an account falls behind, a creditor who originally issued a credit can write it off as a loss (a charge-off) and sell the debt to a third party (a collection). Having these two records on your credit report can pose a serious threat to your score. However, if you notice inaccuracies in a charge-off and collection, you have a legal right to start a dispute on such entries.
The best dispute reason in this case can be:
If the debt does not belong to you.
If the balance or fees are incorrect.
If it’s an old debt (over 7 years from the original delinquency), and a creditor sets a fresher date to present it as a new one.
If the chain of title for this debt is incomplete or missing.
If the debt is already paid, settled, or discharged in bankruptcy.
You have a legal right to request debt validation – a written proof of the debt from a collection party. If information on your credit report is inaccurate or cannot be verified through the credit-report dispute process, it must be corrected or removed.
How to Dispute Late Payments
Records about late payments in a credit report can only be disputed if they are actually incorrect, for example, if you paid it on time or if you’re less than 30 days late on it. To prove an error in such entries, you must provide a bank statement, canceled check, or online receipt that proves that your payment was successfully cleared within the 30-day timeframe.
Here’s what your argument for a dispute can look like:
“The payment for account XXX is marked late, although my bank statement demonstrates that it was processed on November 3, which was only 3 days after the due date of October 31. Marking this payment as late is incorrect, as it was not 30 days past due. Please, update my payment history.”
If you are actually late on a payment, filing a credit dispute letter will not work. In this case, your best bet is a formal goodwill letter that asks the creditor to remove a negative mark due to your good prior payment history.
How to Dispute Hard Inquiries
A hard inquiry appears when you apply for a new credit line, and lenders perform a thorough check of your credit file. Such inquiries can make your score temporarily drop. A soft inquiry, on the other hand, appears during pre-approved offers, routine background checks, and when you check your credit file yourself. Such inquiries don’t affect your score.
According to FCRA, a company must have a permissible purpose to access your credit report. If you notice a hard inquiry entry and know that you didn’t authorize it, you can start a dispute and demand that this entry be removed.
Here’s what you can do:
Confirm that a particular hard inquiry is really unauthorized. Confusion may appear if you applied for a loan with a dealer (e.g., a car dealer) who passed on your application to multiple local banks. In this case, you may simply not recognize the name of a lender in your report. So be sure to contact any dealers that you applied with before starting a dispute.
Create a formal dispute letter stating that you did not authorize a particular credit check.
If you suspect it’s an identity theft case, file an official Identity Theft Report.
File a complaint with the CFPB if the credit reporting agency refuses to remove the unauthorized inquiry.
How to Dispute Identity Theft and Fraud
If you find incorrect entries in your credit report and believe they come from identity theft (for example, if you know your information was in a data breach), this situation requires a number of consecutive and thoughtful steps:
Contact all major credit bureaus and place fraud alerts on your accounts. These alerts will inform potential creditors that your data may be compromised and require them to perform more thorough verifications before they can open a new account or credit line in your name.
Consider placing a security freeze on your report. Unlike fraud alerts, a freeze doesn’t let potential creditors see your credit report at all, making it impossible to open new accounts and credit lines, even if you apply for them yourself.
File an official Identity Theft Report through IdentityTheft.gov: Click report an identity theft, confirm that someone has stolen your information, answer several questions about what kind of information was stolen and what it was used for, and complete a questionnaire with your and the suspect’s data.
Request an identity-theft block under FCRA §605B. After receiving the required identity-theft report, proof of identity, identification of the fraudulent information, and the required statement, the agency must block the information within four business days.
How to Dispute Other Items (Student Loans, Evictions, Child Support, Closed Accounts)
When you dispute student loans on your credit report or another atypical item, such as an eviction, child support, or closed account, it’s important to understand the unique specs of your situation.
Dispute Type | Student loans |
|---|---|
Key Specs | Federal student loans frequently get transferred between multiple companies. This often results in mismatched loan balances and payment histories and/or duplicated accounts. |
When It Can Be Disputed | Duplicate accounts for the same loan Incorrect payment statuses (e.g., a payment is marked late despite an active forbearance) Incorrect loan balances |
Strategic Tips | Go to StudentAid.gov to request a full federal loan history before starting a dispute. Provide federal records as your evidence. |
Dispute Type | Evictions |
|---|---|
Key Specs | The fact of eviction itself does not show up on a credit report. Such records may only appear on tenant screening reports, such as Experian RentBureau. However, if your landlord sells the unpaid rent debt to a collecting agency, it can appear on your credit report as an unpaid bill and remain there for 7 years. |
When It Can Be Disputed | Incorrect debt balance No landlord mitigation of damages (i.e., a landlord rented the apartment to someone else and continued charging rent) The landlord withheld your security deposit but never provided an itemized list of damages. |
Strategic Tips | Request a formal debt validation letter before you dispute an eviction to find violations of your local landlord-tenant law. If your debt is valid, negotiate the “Pay for Delete” option. |
Dispute Type | Child support |
|---|---|
Key Specs | Child support debt cannot be discharged in bankruptcy. You can only dispute it in the event of a factual error. |
When It Can Be Disputed | The debt does not belong to you The reported balance is miscalculated |
Strategic Tips | Start a dispute directly with your local child support agency. Prepare official proof, such as court-ordered modifications and payment confirmations. |
Dispute Type | Closed accounts |
|---|---|
Key Specs | Closed accounts remain in your report for up to 10 years (accounts with positive histories) or 7 years (accounts with negative histories). So you shouldn’t expect them to vanish from your credit report right after you close them. |
When It Can Be Disputed | Incorrect negative marks (e.g., a report says an account was closed by the grantor, but you closed it yourself) |
Strategic Tips | Do not dispute old accounts with positive payment histories because they can shorten your overall credit history and actually lower your score. |
How to File a Dispute With Each Credit Bureau (Addresses and Contacts)
Whenever you detect a credit report error, you need to file a credit dispute letter to one, two, or all three major reporting bureaus – Equifax, Experian, or TransUnion. The strategy should depend specifically on where you detect an error. The thing is that all credit reporting agencies are independent competitors. For this reason, they don’t automatically share information, and even if one agency corrects an error you detected, it won’t disappear from other reports.
Here’s what you should do:
Check all three reports to see if the error is found in one, two, or all of them.
If it only appears in one report, file your letter with the agency you got it from.
If it appears in multiple reports, submit your letter to all agencies that provided you with a report containing incorrect data.
Below you will find the current contact details of each major agency in the U.S.
Experian
Experian credit dispute address | Experian credit dispute phone number |
|---|---|
Experian P.O. Box 4500 Allen, TX 75013 | Call the number displayed on your personal credit report |
Experian credit dispute address | Experian online credit dispute platform |
|---|---|
Experian P.O. Box 4500 Allen, TX 75013 |
Equifax
Equifax credit dispute address | Equifax credit dispute phone number |
|---|---|
Equifax Information Services, LLC P.O. Box 740256 Atlanta, GA 30374-0256 | 888-378-4329 |
Equifax credit dispute address | Equifax online credit dispute platform |
|---|---|
Equifax Information Services, LLC P.O. Box 740256 Atlanta, GA 30374-0256 | https://www.equifax.com/personal/credit-report-services/credit-dispute/ |
TransUnion
TransUnion credit dispute address | TransUnion credit dispute phone number |
|---|---|
TransUnion Consumer Solutions P.O. Box 2000 Chester, PA 19016-2000 | 800-916-8800 |
TransUnion credit dispute address | TransUnion online credit dispute platform |
|---|---|
TransUnion Consumer Solutions P.O. Box 2000 Chester, PA 19016-2000 | https://www.transunion.com/credit-disputes/credit-disputes-faq |
How to Fill Out and Send Your Credit Dispute Letter
Fill out your dispute credit report online using our form:
Step 1. Click Get Form on this Credit Dispute Letter Form page. Our editor will instantly open a fillable form.
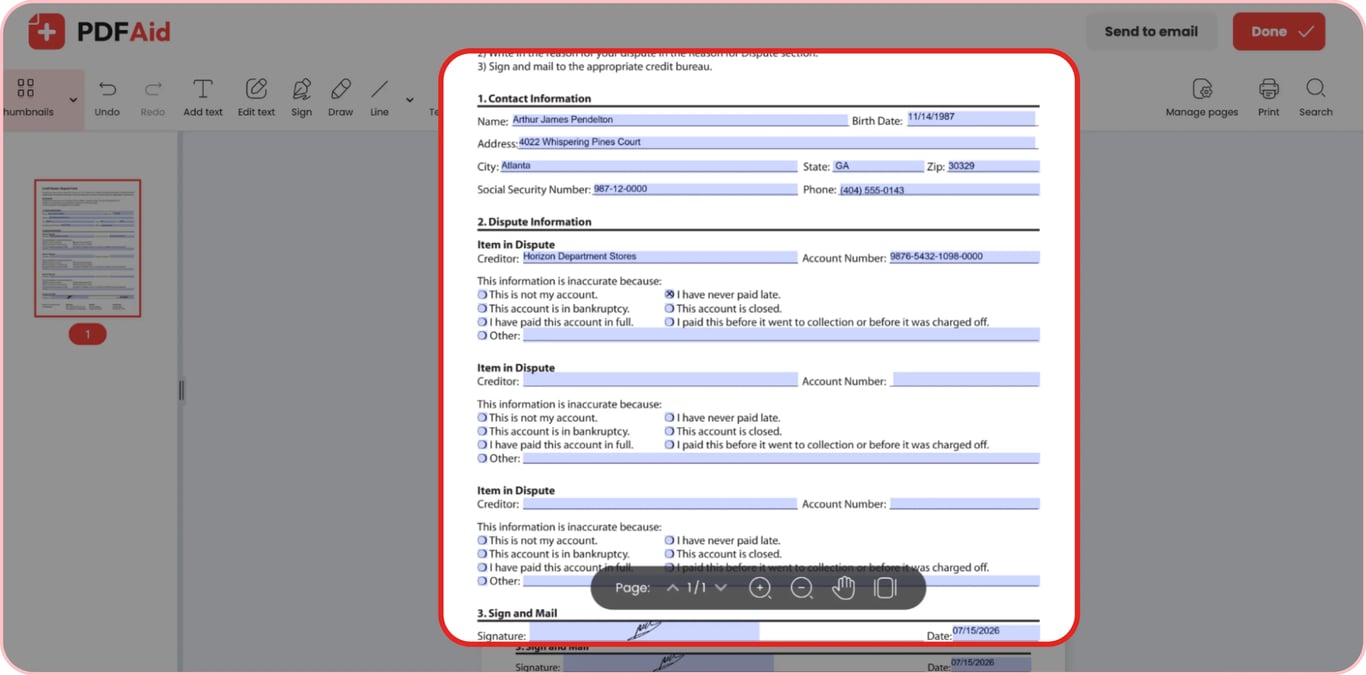
Step 2. Complete the Contact Information section. Be sure to use your full name as stated in the government-issued ID and carefully double-check your mailing address, social security number, and other provided details.
Step 3. Provide the information about each item of dispute you want to cover in your letter. First, type the full name of the creditor and the full number of the account in question. Then, check one of the reasons from the list or check Other and provide a detailed explanation.
Step 4. Review your letter for errors and typos.
Step 5. When everything looks good, click Done in the upper right corner, choose PDF as your preferred format, name the file, and export a copy.
Sign and Send Your Dispute (by Mail or Online)
After you complete the template, you need to add your signature. Doing this with our editor is fast and convenient:
Step 1. Open the completed form in our PDF editor.
Step 2. Go to the last section of the form, click on the signature box, and draw, upload, or type your signature.
Step 3. Type the current date in the relevant field next to a signature.
Step 4. Click Done and export the signed letter as a PDF.
Once you save a copy of a completed and signed letter, you need to file it with the chosen credit agency(ies). You can do this online, via mail, or by phone. The general steps include:
Locate an incorrect entry in your report.
Prepare a formal credit dispute letter and supporting documents, then:
Print them (our form is printable, so you can print it after completing all fields and signing the letter) and mail them to the physical address of an agency.
Go to the dispute platform of a chosen agency, create a personal account, and submit a dispute with your letter and documents.
Or
Have your personal information, report details, and dispute details ready, and file a dispute via phone.
If you decide to submit your letter by mail, consider using certified mail. This method gives you a clear legal proof (Return Receipt) that the chosen bureau received your letter. This way, you have a documented start date of the 30-day investigation window.
Get the most current Credit Dispute Letter – Request for Correction form now
Up-to-date • Fillable • Ready to sign online